
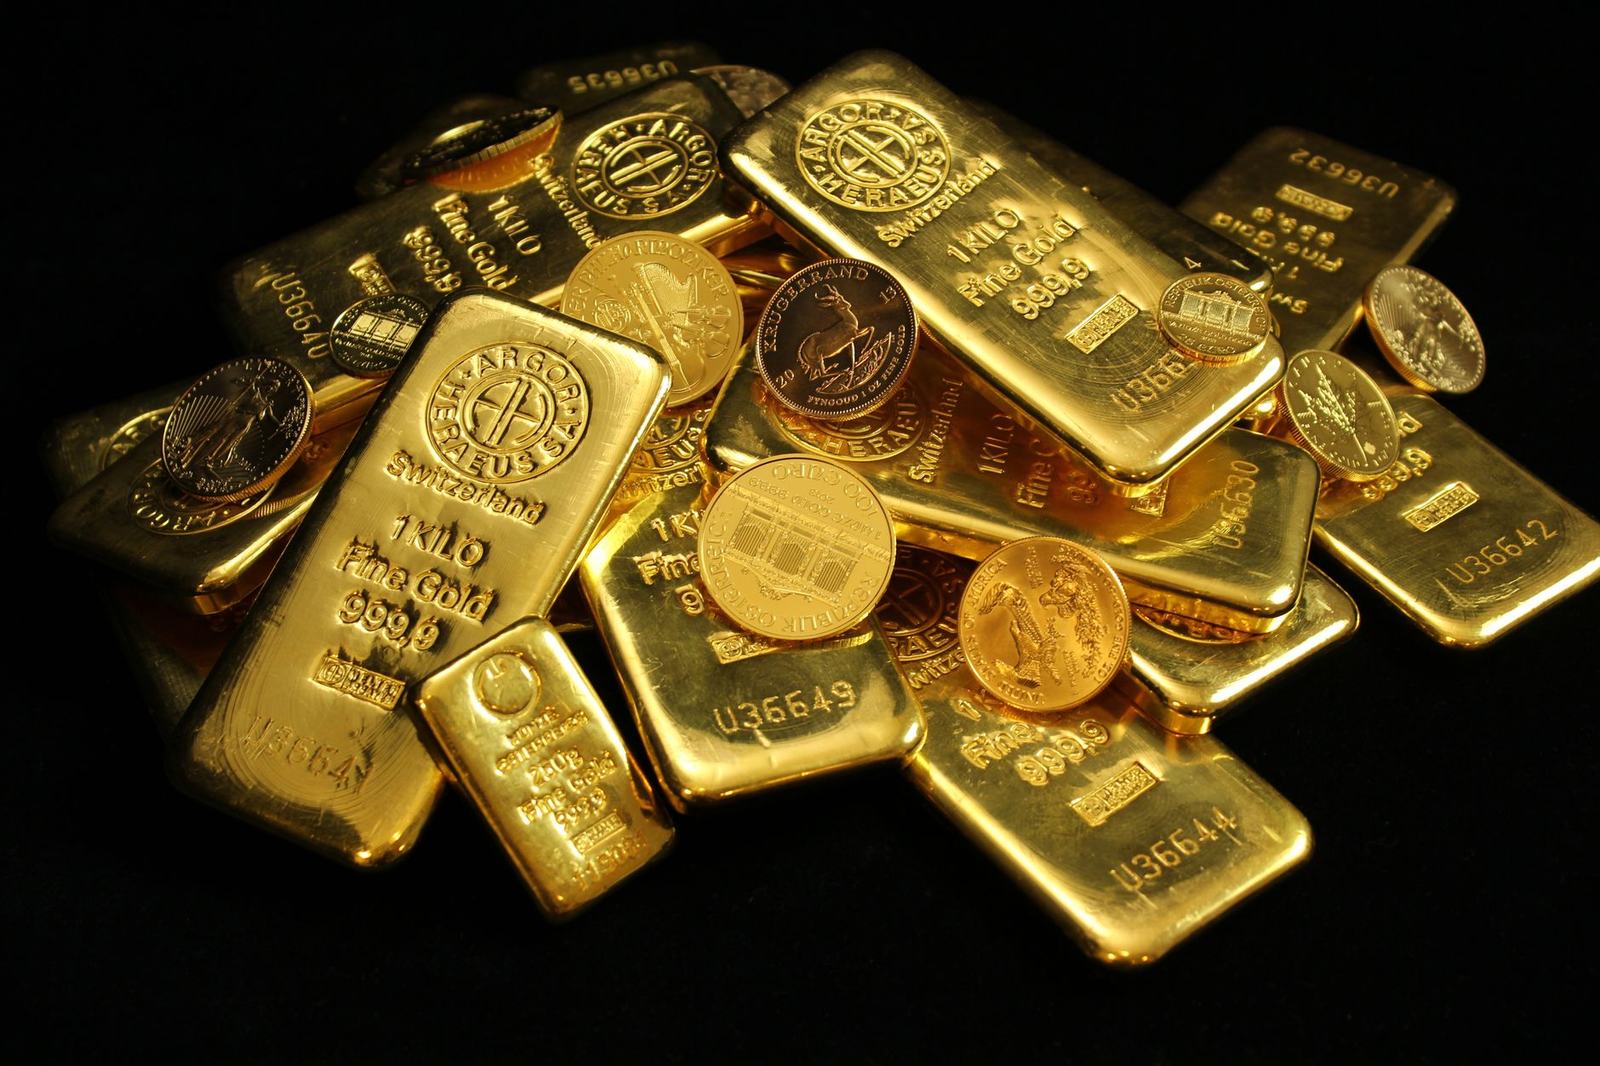
- Tether says KPMG U.S. has examined the assets behind USDT, a with roughly $180bn (about £140bn) in circulation, and physically counted its gold.
- An audit is a look at what existed on a particular date. It is not a promise that every future redemption will be honoured.
- Tether has published quarterly reports for years and promised a full audit for roughly a decade. That history is what makes this news rather than routine paperwork.
The largest in crypto has spent about ten years being asked one question: is the money actually there? Tether now says a Big Four accounting firm has been through its books and counted its gold bars. It is worth knowing exactly what that answers.
If you have ever moved money into USDT to sit out a dip, or used it to get between two trades without going back to sterling, you were relying on a private company’s word that a dollar in means a dollar out. There is no Financial Services Compensation Scheme behind it and no regulator you can ring.
This announcement changes how much of that reliance rests on Tether’s own say-so and how much rests on an outsider checking. That is a genuine shift. It is also narrower than the word “audit” tends to suggest, and the difference is the thing worth ten minutes of your time.
What a stablecoin actually is
Most crypto tokens float. Their price is whatever people will pay, and that is the entire point of them.
A stablecoin is built to do the opposite. It is a token designed to stay pinned to the value of an ordinary currency, almost always the US dollar, so that one unit is worth one dollar today, tomorrow and next year. USDT is the biggest of them by a wide margin.
The reason they exist is plumbing. Moving real money in and out of a bank account is slow, it only works on weekdays, and plenty of crypto exchanges never had proper banking in the first place. A dollar-shaped token that moves on a at any hour solves that. It is why stablecoins are the settlement layer under a huge share of all crypto trading, and why so many people hold them without ever thinking of themselves as holding one.
What “reserves” means, and why the mix matters
The pin to the dollar is not magic. It works because the issuer claims to hold real assets, one dollar’s worth for every token it has created, and to swap tokens back for dollars on demand. Those assets are the reserves.
If the reserves are genuinely there and genuinely liquid, the peg holds because anyone can arbitrage it: buy a token trading at 99 cents, redeem it for a dollar, pocket the difference. If the reserves are short, or tied up in things that cannot be sold quickly, the same mechanism runs in reverse during a rush for the exit.
So composition matters as much as the total. Short-dated US government debt can be sold in minutes at a known price. Corporate loans, other cryptoassets, and gold cannot always be. Tether’s reserve reports have included a mixture over the years, gold among them, which is why the detail about KPMG counting bullion is not a colourful aside. Physical metal is precisely the sort of holding you cannot verify from a spreadsheet.
Attestation, examination, audit: three different things
Here is the distinction that decides what this announcement is worth, and almost nobody spells it out.
An attestation is an accountant confirming a statement management has made. Tether has published these quarterly for years, prepared by outside firms, and they typically say that on one specific day the assets listed added up to at least the tokens outstanding. Useful. Also narrow, because it is a photograph of a single date chosen in advance.
An examination is a step up. The firm gathers its own evidence and expresses its own conclusion rather than simply reporting management’s numbers, but it is still usually pointed at one assertion at one moment.
A full financial statement audit is the thing companies on public markets go through. It covers a period rather than a date, it tests the internal controls that produce the numbers, it examines liabilities as well as assets, and it ends in a formal opinion on whether the accounts give a true and fair view. That is the standard people had in mind whenever they said Tether should be audited.
The words get used loosely, including by companies announcing their own results. When the actual report is published, the questions to ask are simple: does it cover a period or a single date, does it opine on the whole balance sheet or only on the assets, and which KPMG entity signed it? Tether’s announcement refers to KPMG’s US firm. Big Four networks are federations of separate national partnerships, so the name on the cover matters.
What this does and doesn’t cover
Take the announcement at face value and it establishes something real: an independent firm with a global reputation to lose has looked at the assets, including the parts you cannot check remotely, and has been willing to put its name to what it found. For an issuer whose reserves have been argued about for a decade, that is not nothing.
What it does not establish is future solvency. A point-in-time look at assets says what was there when someone looked. It says nothing about what happens if a large share of $180bn is redeemed in a week, whether the less liquid holdings could be sold at the values written down, or how the mix changes the day after the count.
It also arrives via the company that benefits from it. Tether announced the completion; the news is Tether saying the work is done. That is normal corporate communication rather than anything sinister, but the sequence is worth holding in mind. The document, and its scope and caveats, is what settles the matter, not the press statement about it.
Why a decade of promises is the real story
Tether has been promising a proper audit for years. Earlier engagements with accounting firms ended without one being produced. In 2021 the company settled with the New York Attorney General’s office over statements about its backing, paying $18.5m without admitting wrongdoing, and agreed to publish regular reserve breakdowns. It also settled with the CFTC. Those quarterly reports have appeared ever since, and every time one landed, the same criticism followed: this is an attestation, not an audit.
Management has said repeatedly, including under the current chief executive, that a Big Four audit was a priority. It kept not happening, which critics read as evidence something was wrong and the company put down to accounting firms being unwilling to take on crypto clients. Both explanations were unfalsifiable from outside.
That is the correct way to size this news. It is not a new revelation about the reserves. It is the closing of a gap between what the company has said it would do and what it had actually done, which for a company this central to crypto’s plumbing is a genuine change in its standing.
The fight going on around it
None of this is happening in a vacuum. Stablecoins are now the most heavily lobbied corner of crypto, because banks have worked out that a dollar-shaped token paying a return is a deposit competing with theirs. Citigroup’s chief executive Jane Fraser has said she wants US crypto market structure legislation passed, while she and others push for changes, with the question of whether stablecoin holders can be paid rewards still being fought over.
Bigger issuers generally welcome that scrutiny, because compliance costs are easier for the largest player to absorb than for a new competitor. A Big Four name on the reserves is useful in exactly that argument.
If you hold USDT in the UK
Two things are true at once. USDT is enormously useful for what most people use it for, which is parking value briefly without leaving the crypto system. And it is a claim on a private company, not money in a bank.
Sterling in a UK bank is covered up to £85,000 by the FSCS. There is no equivalent behind a stablecoin. If the issuer cannot pay, or an exchange holding your tokens fails, the recovery process is whatever the courts and administrators decide, in a jurisdiction you probably did not choose. Better reserve reporting improves the odds. It does not create protection.
What to watch
The report itself, and specifically its scope: period or single date, assets only or the full balance sheet, which firm signed it, and what the caveats say. If it is a full financial statement audit with an unqualified opinion, that is a first for the sector and a much bigger story than the announcement of it. If it turns out to be a point-in-time examination, that is still an improvement, but not the thing the last decade of criticism was asking for.
After that, whether it repeats. One report is an event. An annual audit, published on a schedule, is an actual change in how the business is run. And whether competitors follow: the moment a Big Four opinion becomes the price of doing business in stablecoins, the ones who cannot get one become visible by their absence.