- CoinDesk reports that the New York Stock Exchange has selected Avalanche as the core settlement ledger for a planned -based stock market.
- The venue does not exist yet and would need regulatory approval before a single share settled on it.
- AVAX rose on the report. It is still down roughly 28% over the past four weeks.
AVAX climbed on reports that the New York Stock Exchange has chosen Avalanche to settle shares. The venue doesn’t exist yet, it would need regulatory sign-off before anything traded, and the word carrying most of the weight in the story is “planned”.
Big institutional names landing on a blockchain and money reaching the people who hold that blockchain’s are two separate events, and they often don’t happen together. If you hold AVAX because of headlines like this one, the question worth asking is whether the proposed system would actually pay fees in AVAX, or simply run on software built by the same company. Nobody has said which.
For UK readers there’s a nearer-term point: a US-regulated venue for tokenised US equities would be built for US brokers and institutions first. It wouldn’t automatically become something you could buy through an FCA-regulated app.
What has actually been reported
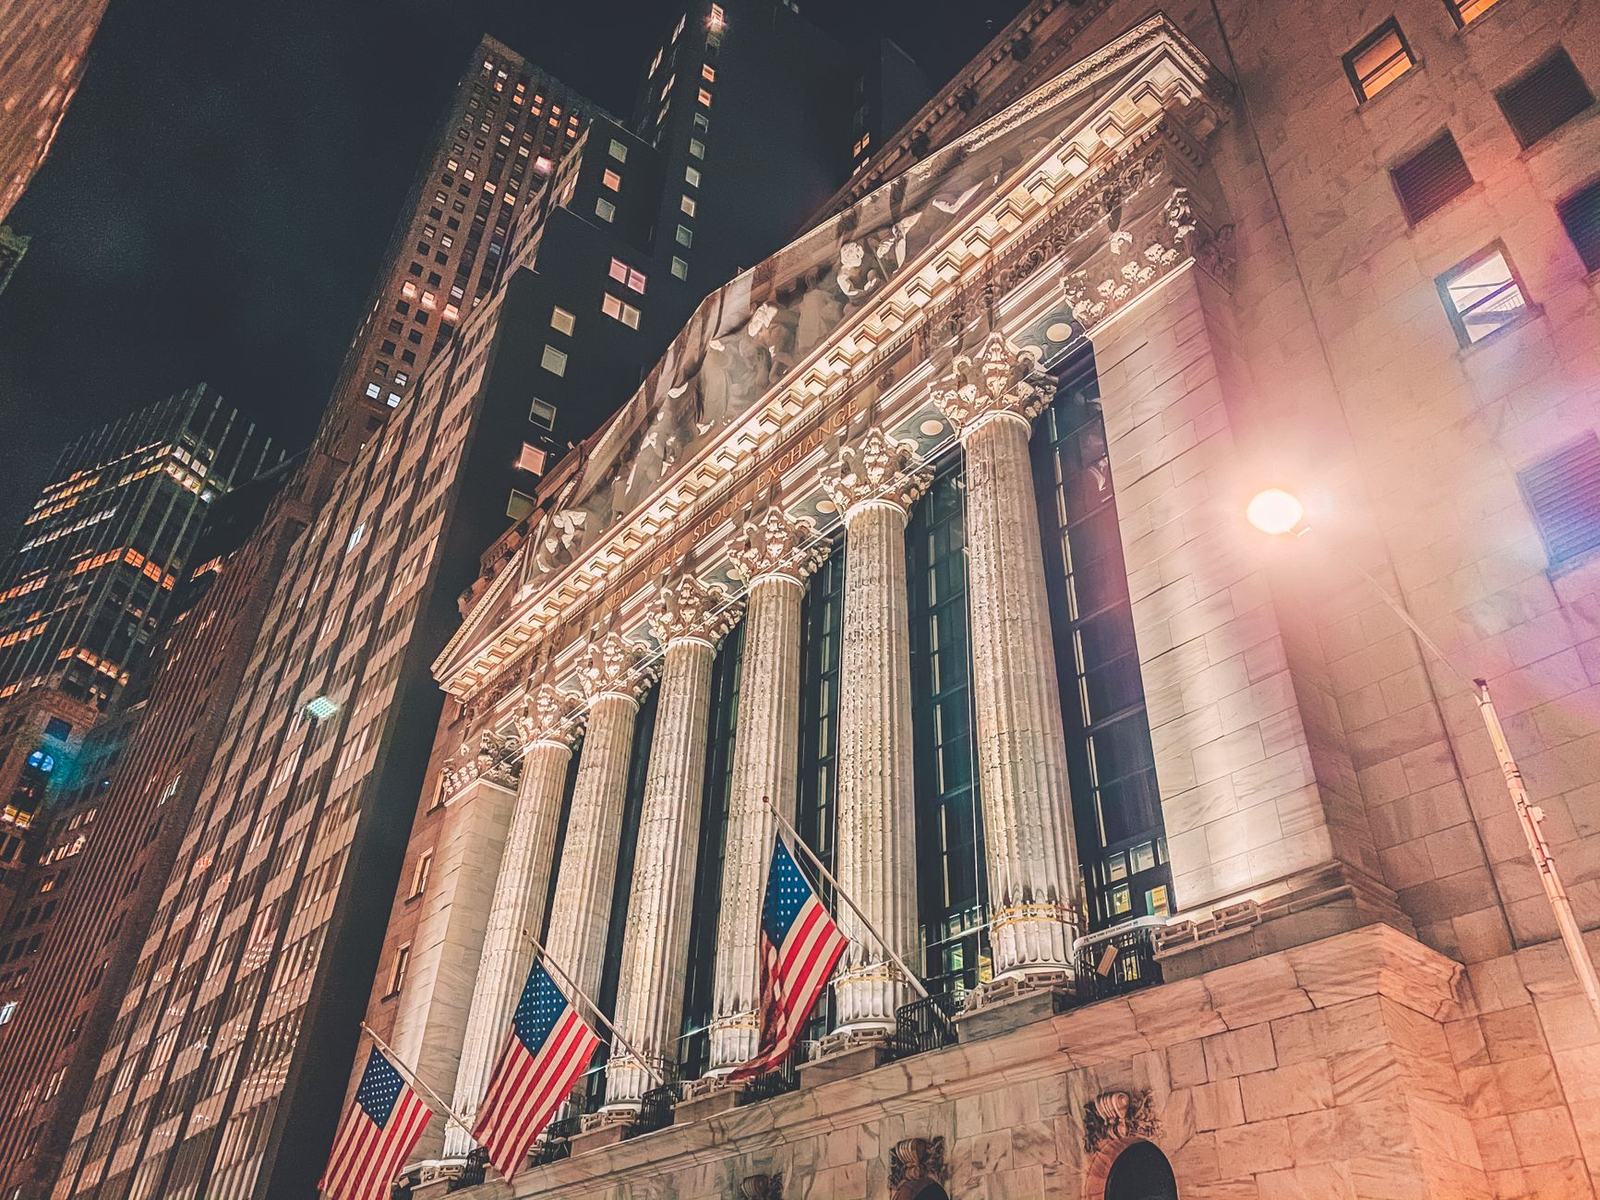
CoinDesk says Avalanche will serve as the core settlement ledger for the exchange’s planned blockchain stock market. We could not find a primary announcement from NYSE, its parent company or the Avalanche side, so every detail in this story rests on one secondary account rather than a document anyone can read.
That matters for how firmly it should be read. “Core ledger technology selected by a clearing affiliate for a venue awaiting approval” and “the NYSE has moved onto Avalanche” are not the same claim, and the second one is the version that tends to end up in a group chat.
What settlement actually means here
When you buy a share today, the trade executes in a fraction of a second and then settles a day later. Settlement is the part where ownership is formally transferred and the cash changes hands, handled in the US by a central clearing house that sits between every buyer and seller.
Putting that record on a blockchain changes where the ledger lives. It does not remove the rest of the machinery. Somebody still has to hold the shares in custody, somebody still has to turn dollars into whatever instrument the venue uses for the cash side, and a broker still sits between you and the venue.
There’s also a trade-off that rarely survives into the headlines. Faster settlement means less netting. Under the current system, brokers offset huge numbers of trades against each other before any money moves, which is why the capital required is far smaller than the daily trading volume. Settle everything instantly and both sides have to have the cash and the shares ready up front. That’s a cost, not a free upgrade, and it’s one of the main reasons institutional tokenisation projects have moved slowly.
What it does and doesn’t mean for AVAX
Avalanche’s design allows separate chains with their own rules, including private ones where access is restricted to approved participants. A regulated clearing operation would almost certainly want that kind of arrangement rather than an open network. The reporting doesn’t specify which, and that gap decides most of the question for holders: a permissioned institutional deployment typically generates licensing and support revenue for the software company, not transaction fees paid in the public token.
That’s our inference rather than anything either party has stated. But it’s the inference the price move implies people aren’t making. AVAX is down about 28% over four weeks, a fall that has nothing to do with this announcement and which the announcement coverage mostly left out.
The race this sits inside
Traditional finance has been circling tokenised equities all year. Intercontinental Exchange, NYSE’s parent, has already been linked to a separate tokenisation effort with the crypto exchange OKX, an idea that drew objections from corporate issuers uneasy about tokens representing their shares being created by parties they hadn’t authorised. Amundi, the European asset manager, announced a share class on Ethereum on 5 November while leaving the investor access and redemption terms unspecified.
At the retail end, the tokenised equity product xStocks said this week it had passed $1bn in assets under management, with more than 1,500 representations of global stocks, up from 60 at launch. That’s the company’s own figure in its own press release, and tokenised stock products of that kind remain unavailable to UK retail investors through regulated channels.
What all of it has in common is that the plumbing is being built well ahead of the permission to use it.
What to watch
A filing. A venue of this kind needs approval from US regulators, and the application is where the structure stops being a press line and becomes a document with specifics in it: who clears, what settles, what the cash leg looks like.
After that, one technical detail worth more than any partnership announcement. Whether the thing runs on the public Avalanche network with fees paid in AVAX, or on a private chain that uses the same software and pays for it in dollars. Until someone answers that, a rising token price is a bet on a question nobody has asked out loud.